The scale of the challenge to achieve net zero is so huge that we need all the best ideas. For hard-to-abate industry executives in the audience, you’re probably looking at energy efficiency as well as alternative fuels. But you’ll still have CO₂ in your process. That’s why we believe carbon capture is a necessary piece of the decarbonization puzzle and CycloneCC, our fully modular technology, will make carbon capture simple, afforable, and scalable.

Urban areas face rising temperatures from the combined effects of climate change and the “urban heat island” phenomenon. Concrete and asphalt trap heat, creating hotter cities, escalating energy demands, and endangering vulnerable populations. To mitigate these effects, solutions must address the problem across all scales: city, neighborhood, street, building, and individual levels.
City-Level Strategies
At the city scale, urban planning focuses on creating cooler environments by improving airflow, increasing plant cover, and reducing heat-retaining surfaces:
- Urban Planning and Cool Corridors: Designing open spaces and cool corridors encourages air circulation and reduces heat concentration.
- Increasing Plant Cover: Initiatives like Paris’ Oasis Project transform schoolyards into green spaces, doubling as cool islands and heat refuges.
- Low-Emission Zones (ZFE): Reducing vehicular traffic in cities cuts emissions, indirectly lowering heat retention.
- Urban Water Management: Large-scale rainwater management systems and urban basins help infiltrate water into the soil. This not only prevents flooding but also encourages evaporation, naturally cooling the air during heatwaves.
Neighborhood-Level Strategies
Neighborhood interventions tackle heat through surface treatments, targeted greenery, and smart solutions:
- High-Albedo Materials: Reflective materials reduce heat absorption, like those used in Paris’ “cool islands.” High-albedo materials are surfaces that reflect more sunlight than they absorb, helping to lower surface temperatures.
- Vegetation and Cool Islands: Projects like Urban Canopée integrate vegetation into neighborhoods, while ENGIE Lab Crigen’s Skycooling panels provide shade-based cooling.
- Water Permeation: Soil desilting and localized rainwater infiltration enhance evaporation, which cools the surrounding air naturally. Incorporating small water features like ponds or fountains within neighborhoods can amplify these cooling effects.
Street-Level Strategies
Streets act as heat hotspots, but targeted solutions can reduce their thermal footprint:
- Draining Pavements: Products like Holcim’s concrete, a permeable concrete Hydromedia, allow rainwater to infiltrate the soil, supporting evaporation and natural cooling.
- Green Walls and Photovoltaic Shades: Vegetated walls and shaded walkways lower street temperatures while improving aesthetics and functionality.
- Localized Water Features: Incorporating fountains, small basins, or artificial streams along streets can provide significant localized cooling effects.
Building-Level Strategies
Buildings are central to urban cooling, as they represent a significant proportion of heat storage:
- Green Roofs: Vegetative layers provide natural insulation and cooling, reducing the heat stored by buildings.
- Reflective Paint: Products like Cool Roof reduce heat absorption, keeping interiors cooler.
- Advanced Insulation: Aerogels, a cutting-edge material known for their lightweight properties and high thermal resistance, can significantly reduce heating and cooling costs by providing superior insulation compared to traditional materials.
- Bio-Reactive Facades: Innovations like XTU Architects’ microalgae facades actively regulate temperature by producing oxygen and absorbing heat.
- Rainwater Harvesting: Buildings can integrate systems to collect rainwater, which can then be used for evaporative cooling or irrigation for rooftop and vertical gardens, further reducing heat buildup.
Individual Actions
Individual behaviors also play a vital role in reducing urban heat:
- Soft Mobility: Walking, cycling, and using public transport help reduce vehicular emissions and heat contributions.
- Urban Greening: Individuals can plant greenery at home, install small water features in gardens, or volunteer for local tree-planting initiatives to enhance cooling.
- Water Stewardship: Households can promote cooling by managing rainwater infiltration with permeable garden designs, rain barrels, or bioswales to ensure water is available for natural evaporation processes.
Cooling urban environments requires a multifaceted approach across different scales. From city-wide planning and water management to individual actions like soft mobility, these strategies not only provide immediate relief from heat but also promote the long-term sustainability of urban life. Addressing the urban heat island effect is a pressing necessity as cities prepare for increasingly extreme temperatures in the decades ahead.
.
2 Key Figures
4
Temperatures can be 1 to 4°C higher than surrounding rural areas due to the presence of heat-retaining infrastructures like concrete and asphalt.
15%
A 10% increase in tree cover in cities reduces surface temperatures and lower energy consumption needs for cooling by around 15%.
.
3 startups to draw inspiration from


CoolRoof
French-based startup specialized in reflective coatings for rooftops and pavements to reduce heat absorption in cities, lowering temperatures and energy consumption.
SolCold
A materials startup from Israel that creates innovative coatings which cool buildings by converting heat into light, reflecting sunlight to reduce urban temperatures.
Green City Solutions
German startup that develops urban green spaces using “CityTree,” a smart, air-purifying moss wall that cools and cleans the air in densely populated areas through IoT integration.
Interested in a startup landscape or in an insights report?
Please fill out our contact form so that we can get back to you very quickly with our product offer.
Want to subscribe to our 123Fab?
Fill out our form to receive the latest insights into your inbox.

Context
Our client has developed a strong innovation activity to fuel its transformation. In this context, our client asked us to explore market demand for a new offering in dismantling and extracting valuable components from lithium-ion batteries.
Mission
We carried out a study to define the go-to-market strategy:
- Map of the second-life battery value chain, from manufacturing to end-of-life
- Segmentation of second-life component buyers
- Real-world applications of second-life components
- Interviews with 8 potential customers on interest and technical needs
- List of existing technical standards for selling second-life battery cells
- Review of the EU battery regulation compliance
- Recommendations on the go-to-market strategy and prioritization of potential customers to address first
Key figures
27
Key players identified
4
Target customer groups
8
Interviews conducted
1
Go-to-market strategy defined

Context
In view of the declining potential of its historical Oil & gas business, our client investigated several diversification opportunities in adjacent markets, consistent with its know-how and energy transition roadmap.
In this context, the Innovation department wanted to evaluate the potential for diversification in the field of Carbon Capture Utilization and Storage (CCUS) and to identify innovative partners with whom to create a complementary business.
Mission
We carried out a deep dive study divided into three steps:
- A market study to paint a complete picture of all the megatrends (new business models, technologies, use cases)
- A startup landscape to identify the innovative players driving CCUS forward worldwide
- A startup scoring to establish recommendations on the most relevant options for collaboration (R&D agreement, commercial partnership, investment, acquisition, etc.)
Key figures
433
Startups sourced in Europe, US & Israel
41
Startups assessed & ranked
5
Partnerships

Context
Our client has developed a strong Open Innovation activity in order to fuel its transformation. In this context, our client asked us to conduct a deep dive study on high-temperature superconductors.
Mission
We carried out a study to define the go-to-market strategy:
- Market study on megatrends and key forces shaping the industry
- Competitor benchmark and illustration of large-scale deployments
- Funding analysis and illustrations of the latest investments
- Patent volume and key patent filer analysis
- Sourcing of all startups in the field
- Interviews with these startups to create fact sheet one-pagers
Key figures
50
Key players identified
36
Live installations mapped
5
Interviews conducted
10
Team members engaged
123Fab #99
1 topic, 2 key figures, 3 startups to draw inspiration from

People generally link global warming with carbon dioxide (CO2) but, as the Intergovernmental Panel on Climate Change (IPCC) explains, 30% of the increase in global temperature since pre-industrial levels is due to higher methane (CH4) concentrations in the atmosphere. This is because methane is extremely more effective at trapping heat.
Where does methane come from?
The IEA has estimated that 40% of methane comes from natural sources (wetlands, biomass burning…), and the remaining 60% from human activities (agriculture, oil & gas production, waste). The two pathways to methane production are:
- Gas leaks – methane is the main component of natural gas. Thus, it can leak from pipelines and drilling.
- Decomposition of organic matter – when organic matter is in oxygen-free environments, particular microbes called methanogens take the lead in breaking down the organisms. This process, called methanogenesis, leads to the creation of methane.
According to McKinsey, five industries could reduce global annual methane emissions by 20% by 2030 and 46% by 2050. Those are agriculture, oil and gas, coal mining, solid-waste management, and wastewater management.
What about methane capture from the air?
Methane is 200 times less abundant in the atmosphere than CO2 — a scarcity that makes removing it a technical challenge. Capturing methane would require processing a lot of air, which could require an extremely large amount of energy. And unlike CO2, which can be captured both physically and chemically in a variety of solvents and porous solids, methane is completely non-polar and interacts very weakly with most materials. However, researchers claim to have found a promising solution. A class of crystalline materials, called zeolites, capable of soaking up the gas. Regardless of this solution, the difficulty of capturing methane from the air is the reason why most technologies focus on oxidizing the greenhouse gas rather than “hooking” it out.
Startups are developing innovations to curb methane emissions
For the decomposition of organic matter:
- in the gut of ruminants (like cows and cattle) – Australian startup Rumin8 and Swedish startup Volta Greentech are fighting this issue by developing seaweed-based nutritional supplements that inhibit methane production.
- on landfills and wastewater – US startup LoCi Controls bolsters the methane capture process using solar-powered devices.
- on wetlands – UK methane capture startup bluemethane has developed a technology to capture methane from water, enabling to mitigate the methane production from rice cultivation.
For gas leaks:
- oil & gas production – UK startup Kuva Systems uses short-wave infrared cameras to autonomously monitor and alert oil and gas companies about methane leaks. Whereas US startup BioSqueeze has developed a biomineralization technology that seals miniscule leakage pathways in oil and gas wells.
- melting permafrost – the trapped organic matter in the frozen seafloors or shallow seas is emitted when they thaw. US startup Blue Dot Change is investigating whether releasing ion particles into the exhaust steam of ship vessels crossing the ocean can accelerate the destruction of methane.
A methane tax just like carbon taxes
Norway was one of the first countries to introduce a carbon tax in 1991. Aside from carbon, the harmful gases regulated by the tax also include methane. All Oil & Gas operators on the country’s continental shelf are now required to report all methane emissions from their activities. As a result, studies show that the country has succeeded to consistently maintain low methane emissions. Canada is proposing to require companies to inspect their infrastructure monthly, fixing the leaks they find as part of efforts to reduce the sector’s methane emissions by 75% by 2030 (compared with 2012). Although the EU is among 150 signatories to the Global Methane Pledge – an agreement to cut emissions of methane by 30% – EU energy chief warned early March that the EU was lagging in the race to curb methane emissions. Since the proposals on methane in 2021, they have been watered down.
In short, methane will be critical to solving the net-zero equation. The good news is that mature technologies are at hand. From feed additives for cattle to new rice-farming techniques, to advanced approaches for oil and gas leak detection and landgas methane capture. Where costs are prohibitive, there is a need for coordinated action to create the infrastructure and fiscal conditions that would support further action. Finally, across the board, there is a need for more monitoring and implementation.
2 Key Figures
Budget of $60-110 billion annually up to 2030
Full deployment of the methane abatement measures would cost an estimated $150-$220 billion annually by 2040 and $230-$340 billion annually by 2050.
< 100 funded companies
Tracxn
3 startups to draw inspiration from

Kayyros
French-based startup founded in 2016 which is a developer of an energy analytics platform for traders, investors, operators and governments. Kayrros powers part of the Global Methane Tracker.

BioSqueeze
US-based startup founded in 2021 that has developed a biomineralization technology that seals miniscule leakage pathways in oil and gas wells.

Rumin8
Australian-based startup founded in 2021 which is a manufacturer of seaweed-based nutritional supplements for livestock that inhibit methane production. The startup is backed by Bill Gates’ fund Breakthrough Energy Ventures.
Interested in a startup landscape or in an insights report?
Please fill out our contact form so that we can get back to you very quickly with our product offer.
Want to subscribe to our 123Fab?
Fill out our form to receive the latest insights into your inbox.

Among the numerous decarbonization solutions under development, three major carbon capture applications stand out today: industrial point source carbon capture, direct air capture (DAC) and bioenergy with carbon capture. Although industrial point source carbon capture appears to be the main focus for most decarbonization roadmaps thanks to increasingly mature and cost-effective technologies driving greater deployment across industrial sites, several challenges must be addressed before it can reach sufficient scale, including policy and regulatory support, access to funding, public acceptance and further cost improvement.
Carbon Capture-as-a-Service (CCaaS) is a business model that is gaining ground in part to circumvent the huge CAPEX hurdles encountered in these type of infrastructure projects. By opting for a one-stop shop solution that handles the entire value chain, hard-to-abate industries can pay to capture their CO2 emissions on a per-ton basis, while other specialized actors take on the risk (and potential financial reward) of managing the full value chain from capture to utilization or storage.
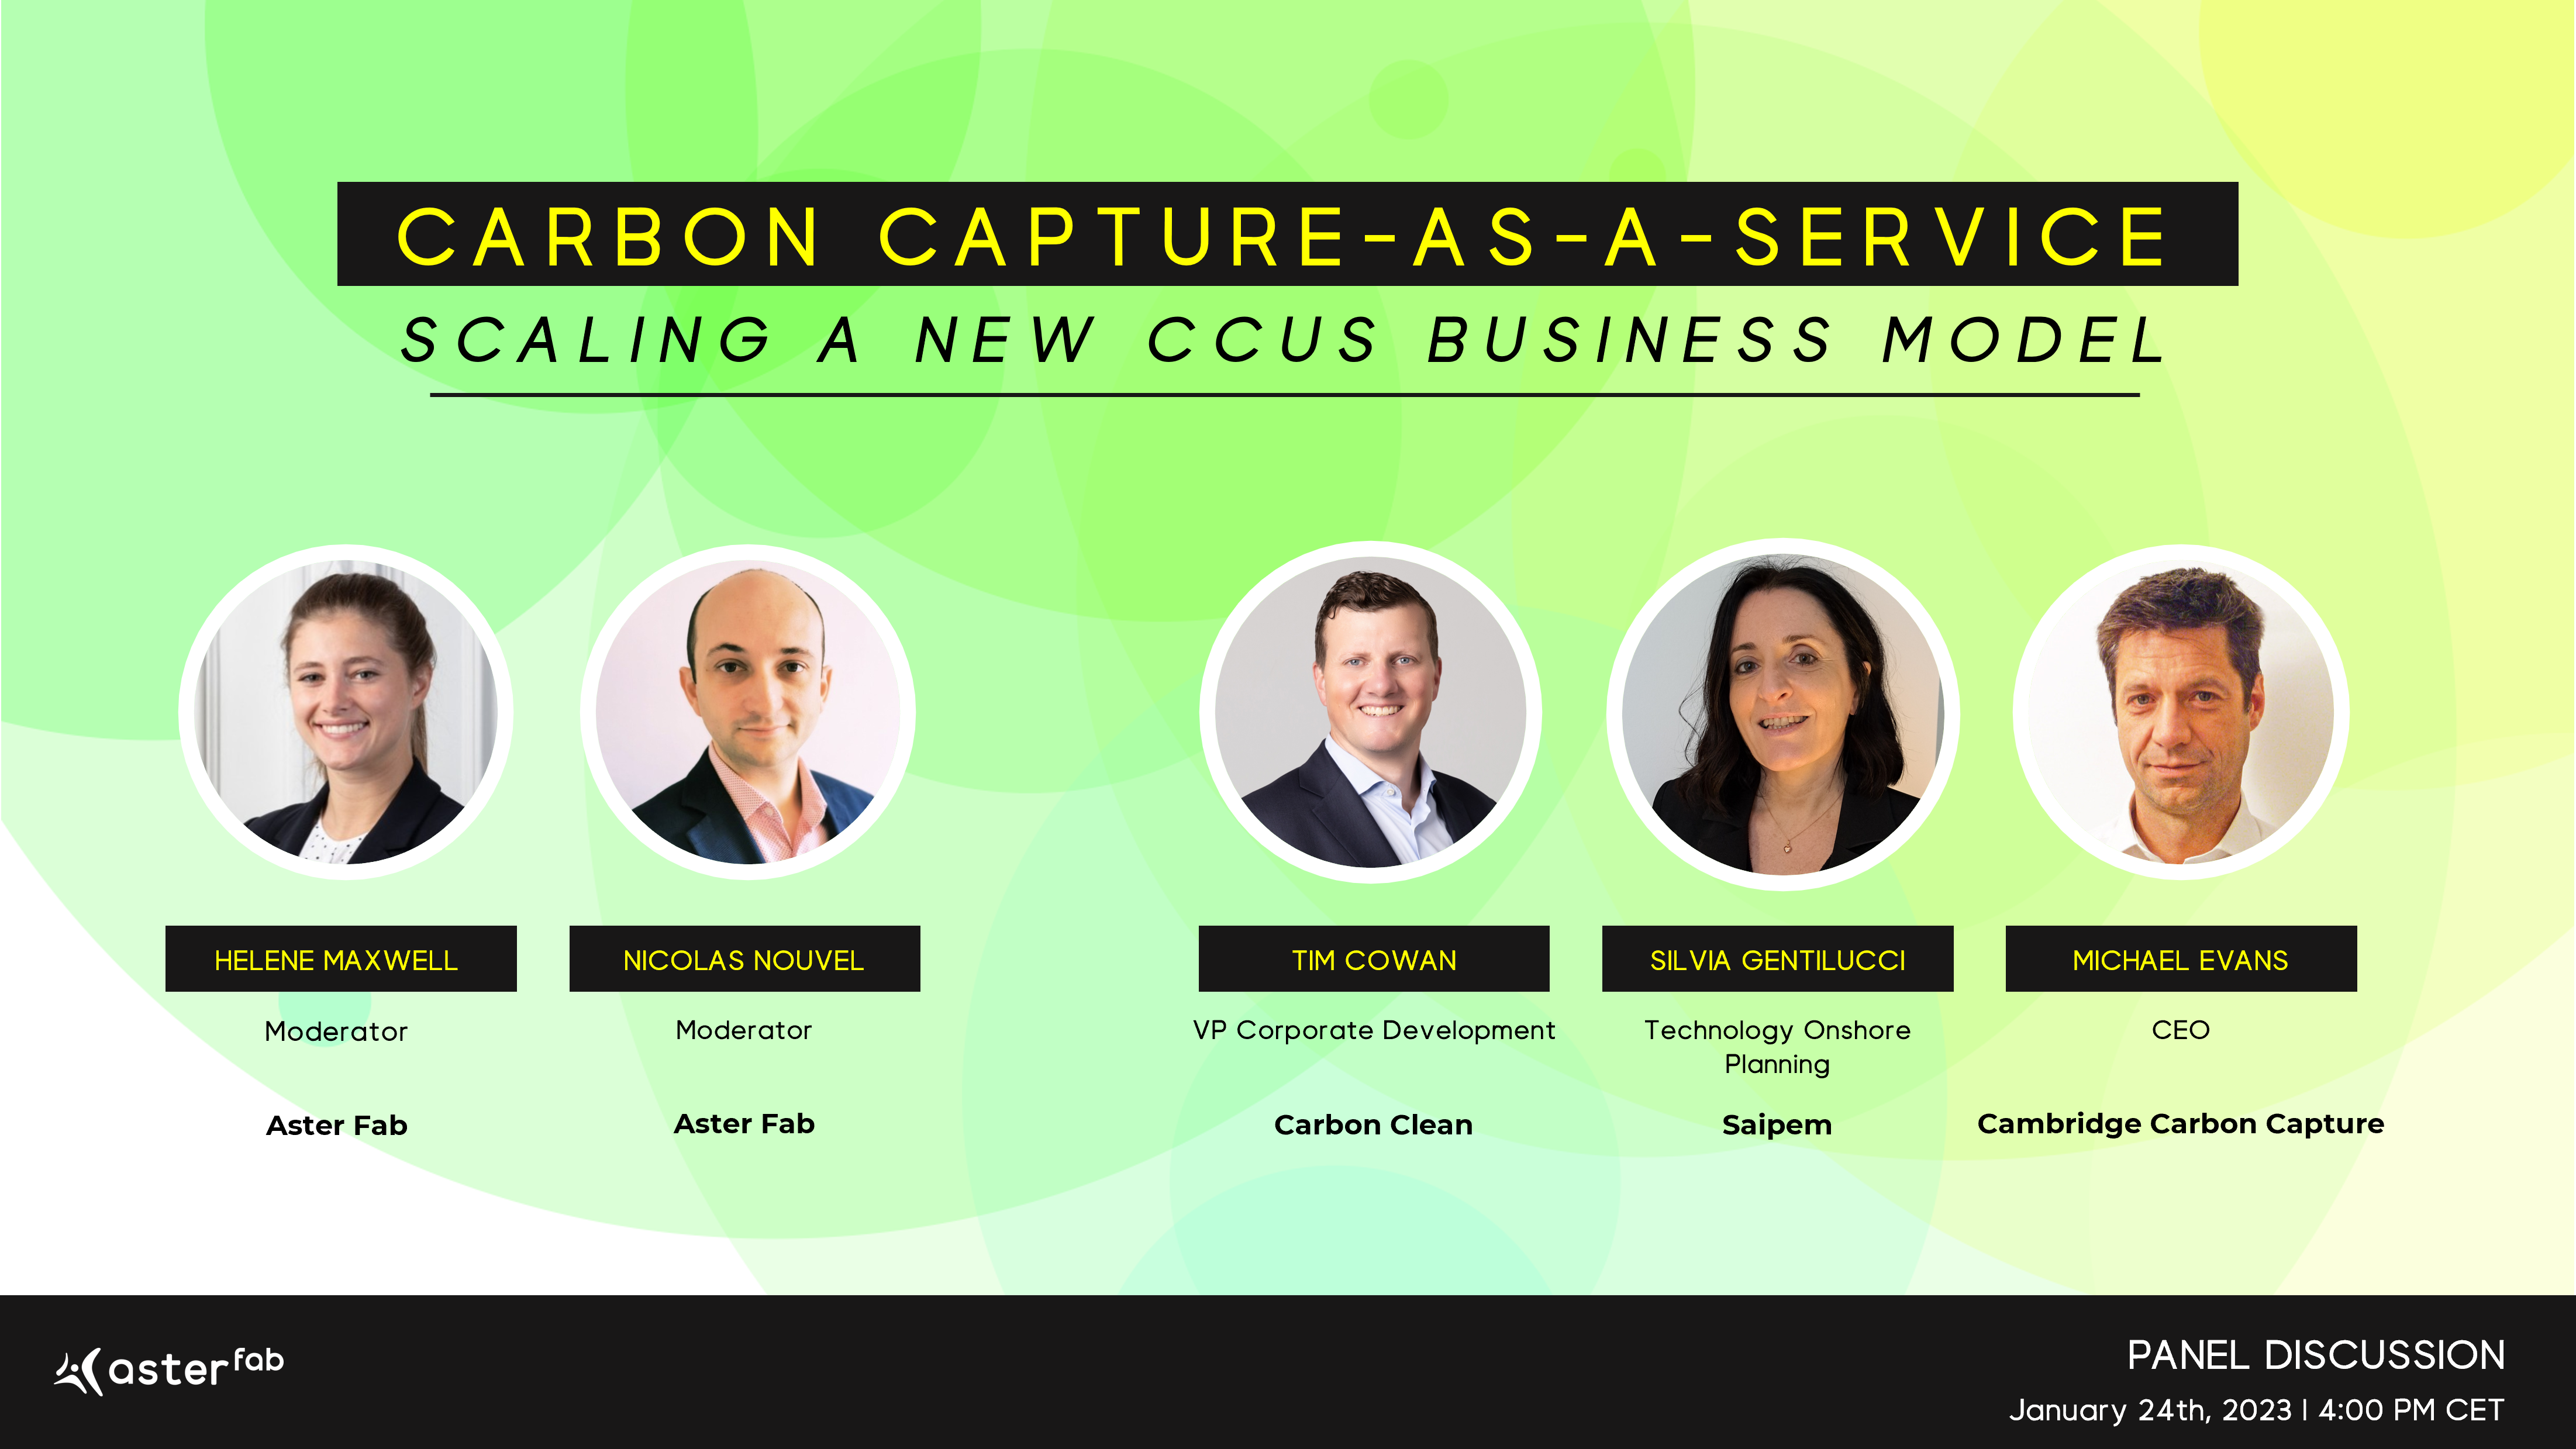
In January, Aster Fab moderated a panel featuring Tim Cowan (VP Corporate Development at Carbon Clean), Silvia Gentilucci (Technology Onshore Planning at SAIPEM) and Michael Evans (CEO of Cambridge Carbon Capture) to discuss the strengths and prospects of the CCaaS business model.
Takeaways from the discussion included:
CCUS adoption must increase 120-fold by 2050 for countries to meet their net-zero commitments
According to the latest Global Carbon Budget published in November 2022, if emissions are not reduced through decarbonization technologies such as Carbon Capture Utilization and Storage (CCUS), the world will have exhausted its 1.5°C carbon budget – the cumulative amount of CO2 emissions permitted over a period of time to keep within the 1.5°C threshold – in nine years. Indeed, the equation highlighted is quite simple: there are about 380Gt of CO₂-equivalent emissions left in the 1.5°C budget, and right now we use just over 40Gt of it each year.
As such, CCUS is recognized as a necessary piece of the decarbonization jigsaw, but the adoption isn’t moving fast enough. According to a McKinsey analysis, CCUS adoption must increase 120-fold by 2050 for countries to achieve their net-zero reduction goals, reaching at least 4.2 gigatons per annum (GTPA) of CO₂ captured.
Carbon Capture-as-a-Service (CCaaS): shifting capital cost to service providers, thereby allowing emitters to focus on their primary activities
In 2021, Decarb Connect conducted a benchmarking survey of industry attitudes towards CCUS that revealed that 65% of executives working in hard-to-abate industries see CCUS as ‘critical’ or ‘important’ for reaching their 2030/2050 goals. It also reveals that 41% are favorable to as CCaaS model, while 59% prefer a mix of funded and owned CCUS. In other words, no executive opted for the traditional model of owning and operating the infrastructure themselves.
Thus, the CCaaS business model appears to be a promising way to accelerate the adoption of carbon capture technology for industrial players:
- No required upfront capital expenditure
- Duty to contract with each player of the value chain is delegated
“At Carbon Clean, we use our leading technology to capture CO₂. and will work with partners to provide the other crucial elements of the value chain: compression, transportation, sequestration or utilization. Our mission is to work with industrial partners to offer an end-to-end handling of our customers’ CO₂.” Tim Cowan, VP Corporate Development at Carbon Clean.
Scaling the CCUS industry will require action by governments and investors
Tax credits, direct subsidies and price support mechanisms are beginning to encourage investment in CCUS. The US, for example, has a 45Q-tax credit that provides a fixed payment per ton of carbon dioxide sequestered or used. The IRA (Inflation Reduction Act) has increased the amount of the credit from $50 to $85 a ton for sequestered industrial or power emission, and from $50 to $180 a ton for emissions captured from the atmosphere and sequestered. In other words, they provide a direct revenue stream immediately improving the investment case for low-carbon technologies, such as CCUS. What the IRA calls tax credits, the EU calls State Aid. Yet, the panelists affirm that while the EU led the whole decarbonization movement for 30 years, the EU is now behind in terms of policy.
It is going to be very challenging for CCUS as it currently stands to make the whole thing stack up. I don’t think the carbon tax will be the viable way forward in the long-term. We need other incentives, as the US are currently doing with the IRA. Many innovative policies are starting to come out of the US and this will encourage innovative companies to set up operations there, giving the US a competitive advantage over the UK and EU in what will become a significant new industry.
There is a need to scale the whole carbon capture value chain
Another element is the uneven distribution of storage sites across Europe. Often illustrated as the ‘chicken and egg’ paradox, there is a need to scale the value chain as a whole, including storage infrastructure. Indeed, a carbon capture plant will not start operating until the captured CO₂ can be transported and then either permanently stored or used. Similarly, no large-scale carbon storage project will be financed without clear commitments regarding the origin and volume of CO2 to be stored, as it determines the financial viability of the overall project.
In Italy, there are plans to build infrastructure using depleted reservoirs in the Adriatic Sea for local storage of CO₂. Without adequate transportation and storage infrastructure, industry will not be able to adopt carbon capture technologies.
Norway’s Longship project, which is sponsored by the Norwegian government, aims to solve this problem by supporting the whole value chain from carbon capture to transportation and storage. Captured emissions will be transported by tankship and stored deep underground using Northern Light’s open-access CO₂ transport and storage infrastructure.
Garnering public support
Finally, speakers also emphasized that addressing public concerns around the safety of these technologies will be paramount. Communicating that carbon capture is safe, effective and a needed method of climate change mitigation, can help bring people on-board and ensure that projects overcome development hurdles. “I think honesty in the media about the situation would be a true incentive. If the public understood how urgent the situation is, and understood more about the technology, there would be a lot more action”. Michaels Evans, CEO of Cambridge Carbon Capture

Context
Our client was the M&A department of a leading nuclear company.
Until now, the department had always taken majority stakes in established companies. However, an interesting opportunity for a minority investment in an innovative start-up was presented to them by a Business Unit of the group.
Aster Fab’s mission was to assist the department in evaluating the opportunity and then in structuring the investment proposal.
Mission
- Valuation of the startup using five different methods (comparable company analysis, precedent transactions, DCF analysis, R&D headcount, replacement cost value)
- Creation of a business plan in coordination with the Head of Business Unit to identify the business potential of such a partnership
- Structuring the investment proposal by drafting the letter of intent setting out the terms, governance, management package, performance criteria, etc
- Assistance, coordination and negotiation with all stakeholders throughout the process
- Support in the preparation of separate documents for the governance bodies
Key figures
3.4 M€
contribution
was the conclusion of the business plan exercise
50%
of the financing needs
the challenge of the business plan enabled to halve the financing needs announced by the founders